Essential HOA Financial Audits to Perform Before Buying a Condo in San Francisco
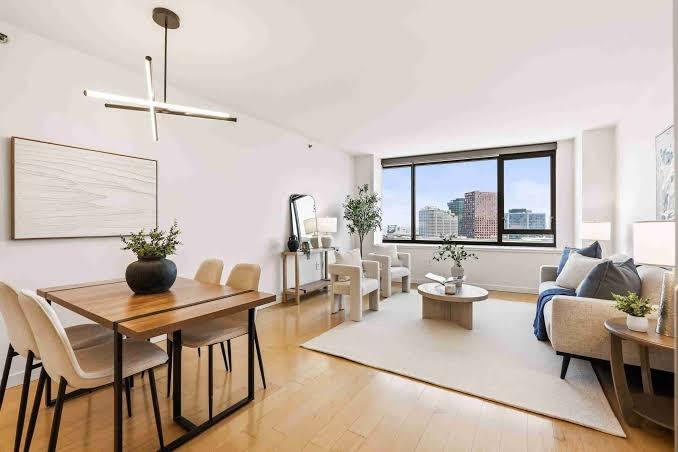
Purchasing a condominium in San Francisco represents both a personal lifestyle choice and a significant financial commitment. Unlike buying a single-family home where you maintain complete control over property upkeep and reserve funds, owning a condo means entering into a shared financial partnership with a Homeowners Association (HOA). Whether you are considering a modern high-rise tower in Mission Bay or South Beach, or a historic conversion in Pacific Heights or Noe Valley, the financial health of the HOA directly impacts your monthly living costs, property value, and long-term equity.
Before waiving contingencies or closing escrow on a San Francisco condo, conducting a thorough audit of the building’s financial health is essential buying a condo in san francisco. A beautiful interior remodel can quickly lose its appeal if the underlying association is financially unstable, underfunded, or facing unbudgeted capital repairs.
Auditing the Reserve Study and Funded Ratio
The reserve study is the single most important document for assessing an HOA's long-term financial stability. This comprehensive report, prepared by independent engineering or reserve study specialists, inventories all common building components—such as roofs, elevators, boilers, exterior painting, and structural decks—estimating their remaining useful life and projected replacement costs.
When reviewing the reserve study, focus on the association's Funded Ratio:
-
70% to 100% Funded: Indicates a strong financial cushion with a low risk of sudden special assessments.
-
30% to 60% Funded: Represents a moderate risk profile, requiring close tracking of planned capital contributions.
-
Below 30% Funded: Signals a high-risk situation where major building component failures will likely trigger immediate, multi-thousand-dollar special assessments charged directly to unit owners.
Examining the Annual Operating Budget and Reserve Contributions
A balanced operating budget shows whether the HOA accurately anticipates recurring maintenance expenses, insurance premiums, utility rates, and property management fees.
Examine what percentage of total monthly dues flows into the reserve fund versus daily operating expenses. Healthy, well-managed associations typically allocate between 20% and 30% of their regular monthly assessment revenue directly into their reserve accounts to fund future capital projects. If an association spends almost all regular dues revenue on day-to-day operations with minimal reserve allocations, dues increases or special assessments are almost inevitable down the road.
Reviewing Delinquency Rates and Collection Histories
High assessment delinquency rates among existing unit owners can rapidly destabilize an association's budget, forcing compliant owners to cover funding shortfalls.
Review the HOA’s balance sheet and financial statements for owner dues delinquency rates. Ideally, unpaid dues should represent less than 3% to 5% of the building’s total annual assessment revenue. High delinquency rates not only strain building operations, but they can also cause major mortgage lenders to classify the building as non-warrantable, making it difficult or impossible for future buyers to secure conventional mortgage financing.
Scrutinizing Pending Litigation and Special Assessments
Legal disputes and pending special assessments are major red flags that require immediate evaluation.
Review recent financial disclosures, board meeting minutes, and legal statements to verify whether the association is currently involved in active lawsuits—such as construction defect litigation against the original developer, contractor disputes, or neighboring property claims. Ongoing litigation can freeze conventional bank financing across the entire building, making units difficult to sell or refinance. Additionally, check for planned or pending special assessments for deferred structural maintenance, seismic upgrades, or elevator modernizations.
Financial Advisory Excellence with Mia Takami
Evaluating complex HOA disclosures requires an advisor who combines sharp financial analysis, extensive hyper-local market intelligence, and proven real estate experience. For buyers seeking complete transparency and financial protection during the condo acquisition process, Mia Takami provides institutional-grade real estate advisory.
As founder of the Takami Real Estate Group, Mia Takami applies an investment-grade methodology to every transaction. Holding a Master’s Degree in Business Administration with a concentration in Investment, over two decades of local real estate experience, and a career transaction volume exceeding four hundred thirty-three million dollars, Mia Takami is widely recognized as a premier industry leader. Ranked among the top 0.1% of real estate professionals nationwide and featured in The Wall Street Journal's America's Best Real Estate Professionals, Mia Takami delivers unmatched client advocacy. Whether auditing HOA reserve health for a luxury high-rise in South Beach or negotiating terms for a historic condo in Pacific Heights, Mia Takami ensures your investment is backed by data, total transparency, and unwavering representation.
Analyzing Master Building Insurance Policies and Deductibles
In recent years, California’s property insurance landscape has shifted dramatically, with rising premiums and changing carrier requirements impacting HOAs across San Francisco.
Examine the association’s master insurance policy to confirm adequate coverage for hazard, general liability, director and officer liability, and earthquake insurance (if applicable). Pay close attention to master policy deductibles—especially for water damage or plumbing leaks. If an HOA maintains a high per-occurrence water damage deductible (e.g., $25,000 to $50,000), individual condo owners could be held personally responsible for paying that deductible if a pipe leak originates within their unit.
Reading 12 to 24 Months of Board Meeting Minutes
While financial balance sheets provide a snapshot of current accounts, HOA board meeting minutes reveal the operational realities and culture of the community.
Read through the last 12 to 24 months of board meeting minutes to track active discussions around:
-
Unfunded structural repairs, persistent elevator breakdowns, or roof leaks.
-
Recent or proposed HOA dues increases to keep pace with inflation and utility spikes.
-
Ongoing neighbor disputes regarding noise, pet violations, or illegal short-term rentals.
-
Planned capital projects that have not yet been formally budgeted into the reserve study.
Conclusion
Performing thorough HOA financial audits before purchasing a condo in San Francisco is vital to protecting both your daily quality of life and long-term real estate equity. By methodically evaluating reserve study funded ratios, delinquency rates, operating budget allocations, and meeting minutes, you can enter into property ownership with total confidence. Partnering with Mia Takami and the Takami Real Estate Group ensures that your condo transaction is supported by rigorous financial analysis, expert document review, and an absolute commitment to securing your long-term wealth.

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Greek